
UPI-FIRST CHECKOUT Make UPI the natural next step
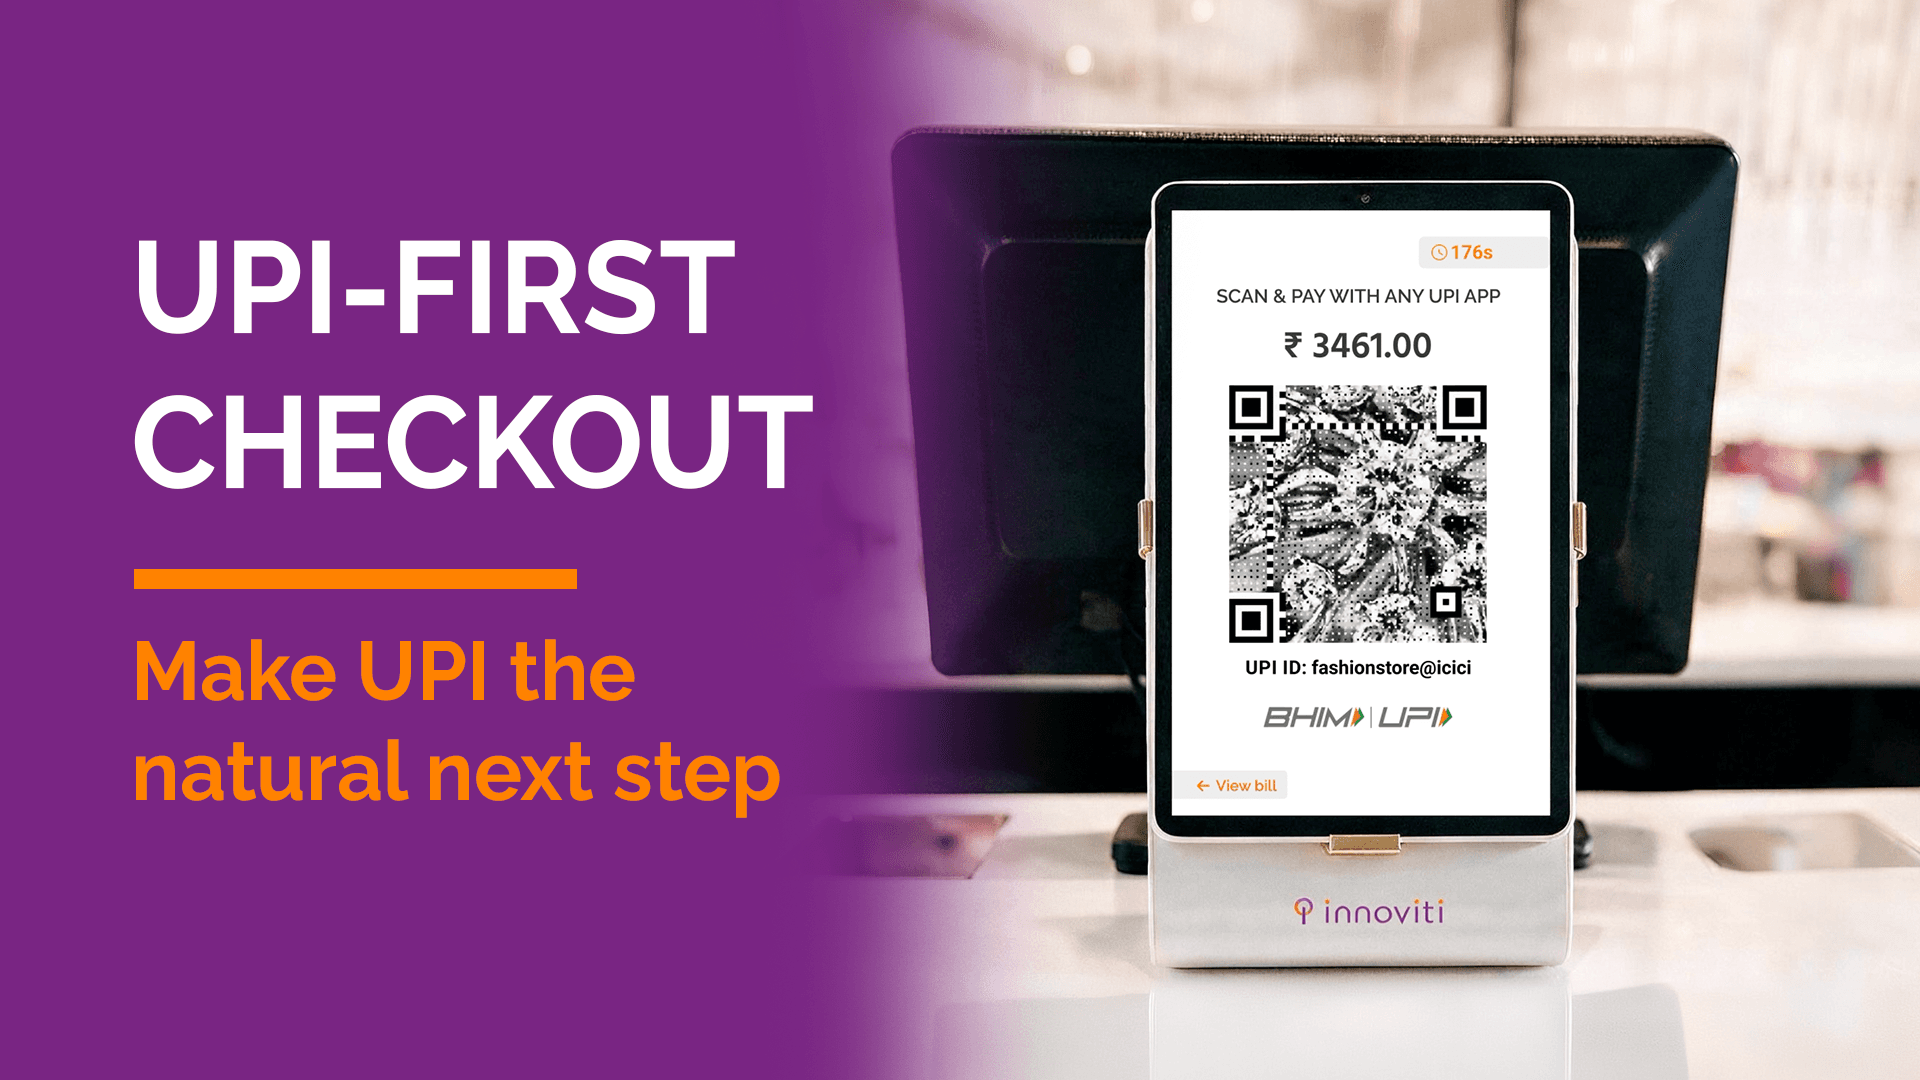
Make UPI the natural next step at checkout
Digital payments have transformed retail. Customers can now choose from cards, UPI applications and a growing range of payment-linked offers. Yet the final interaction at many checkout counters remains largely unchanged: once billing is complete, the cashier asks, “Card or UPI?”
How those options are presented can influence what the customer chooses. A UPI QR displayed on a small, cashier-facing terminal—or through a static sticker at the counter—can be easy to miss. Customers may therefore select a card out of habit, even when UPI would be equally convenient and more cost-efficient for the retailer.
UPI-First Checkout redesigns this moment. Innoviti’s customer-facing payment solution connects the retailer’s billing system, existing payment terminal and an additional large display to create one continuous journey from bill review to payment.
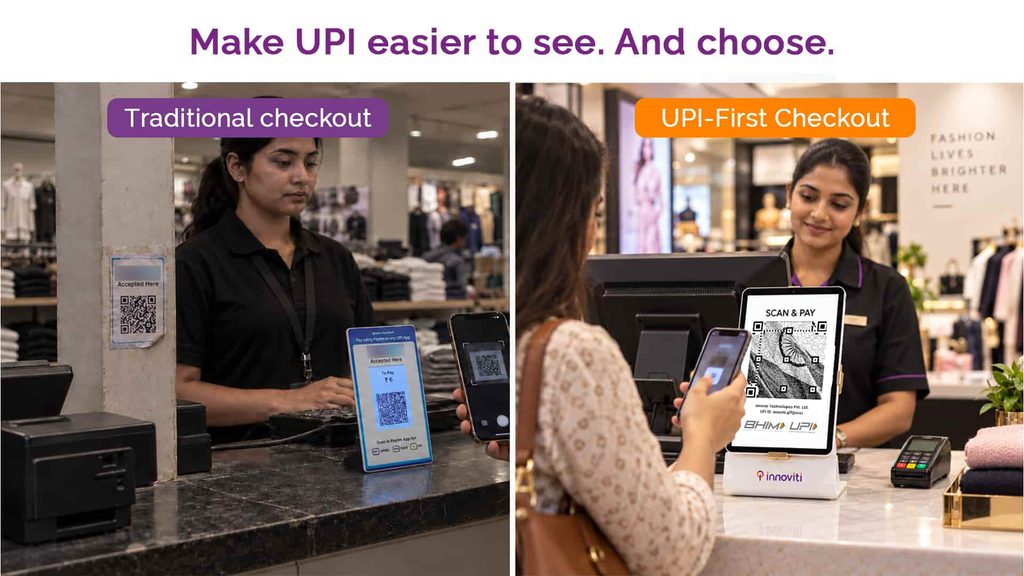
UPI is available at checkout. It is not always presented effectively.
At a conventional checkout, the payment journey depends on a conversation between the cashier and customer. This introduces an additional decision at the end of the transaction and gives habit a strong influence over the final payment method.
| AT CHECKOUT | Traditional checkout | UPI-First Checkout |
|---|---|---|
| Start | Cashier asks, “Card or UPI?” | Review the bill and press Pay |
| Next step | Choose a payment method | UPI appears automatically |
| QR visibility | Small, passive or hard to notice | Large dynamic QR, facing the customer |
| Payable amount | May need manual entry | Exact payable amount built into the QR |
| Payment habit | Cards may be chosen out of habit | UPI is the prominent, convenient path |
| Branding | Generic payment interface | A branded customer experience |
| Privacy | Mobile number may be spoken aloud | Private number entry supports DPDP-aligned data capture |
| End-to-end flow | Separate billing and payment | One connected journey, from bill to payment |
From payment choice to a connected journey
UPI-First Checkout does not restrict payment choice. It gives UPI the first opportunity to complete the transaction while keeping card payment available through the existing terminal.
UPI-First Checkout does not restrict payment choice. It gives UPI the first opportunity to complete the transaction while keeping card payment available through the existing terminal.
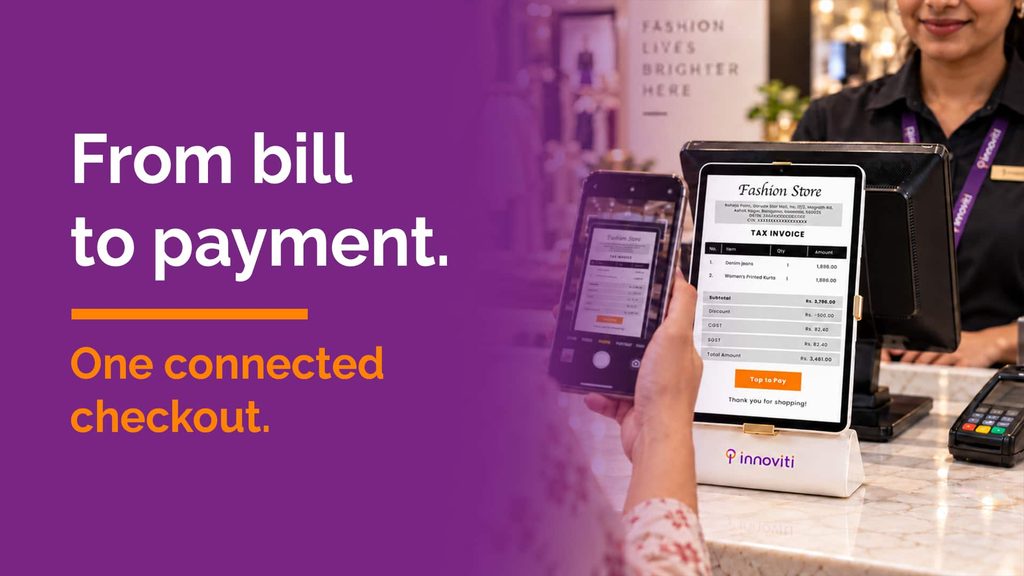
Powered by Innoviti’s Advanced Billing Integration
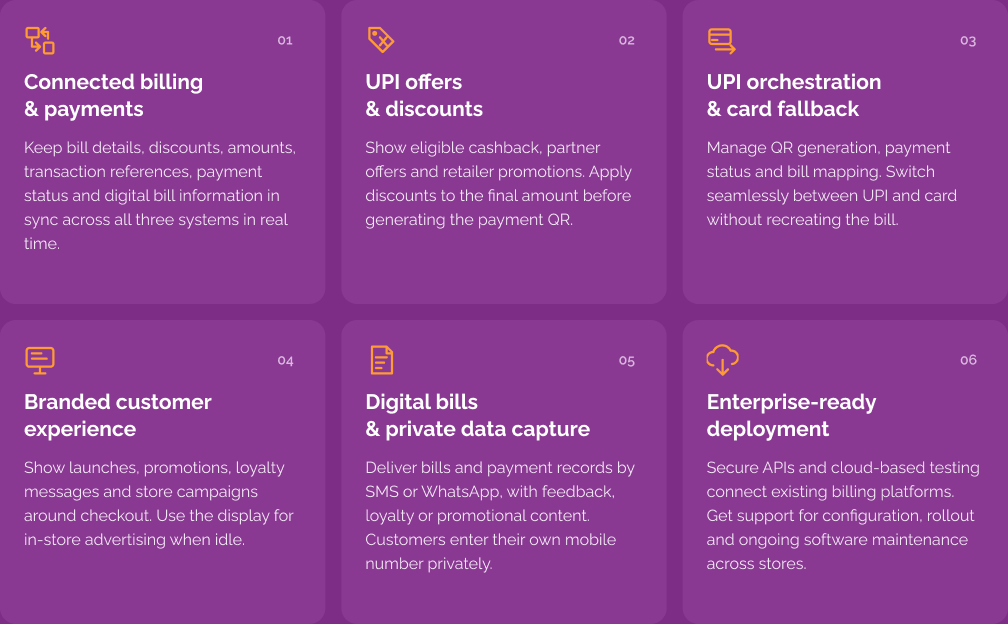
UPI-First Checkout operates through Innoviti’s Advanced Billing Integration: a secure, API-based technology layer connecting the retailer’s billing application, customer-facing display and existing payment terminal.
Conventional terminal integrations typically transfer only the payable amount from the billing application to the payment device. Innoviti’s integration coordinates the broader checkout journey—including bill display, applicable offers, payment initiation, dynamic QR generation, payment-mode switching, transaction status and digital document delivery.
The retailer’s billing system remains at the centre of the transaction. Store teams continue using their familiar billing process, while Innoviti manages the connected customer-facing experience without requiring the retailer to replace its existing billing software or card-payment infrastructure.
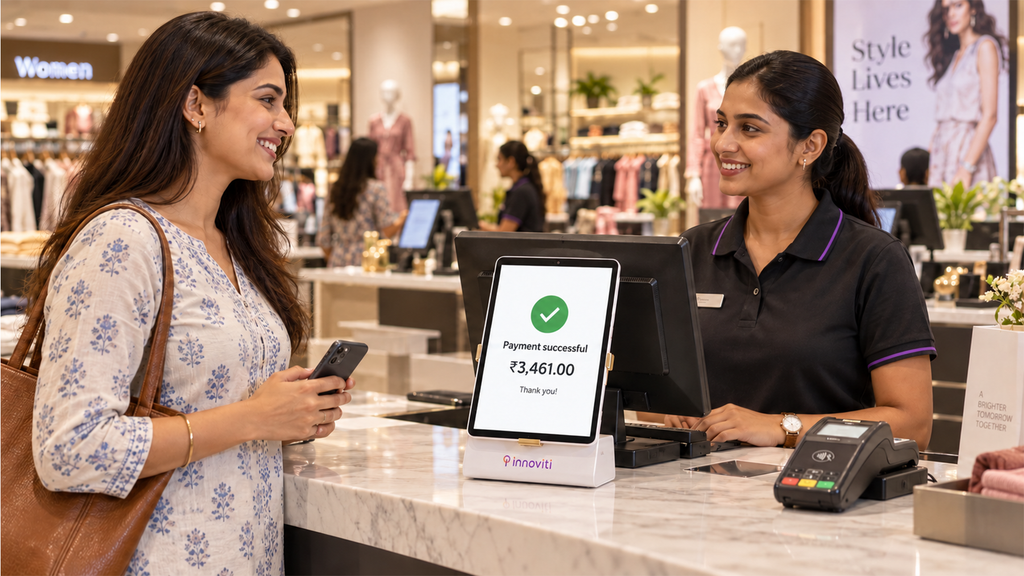
The customer journey
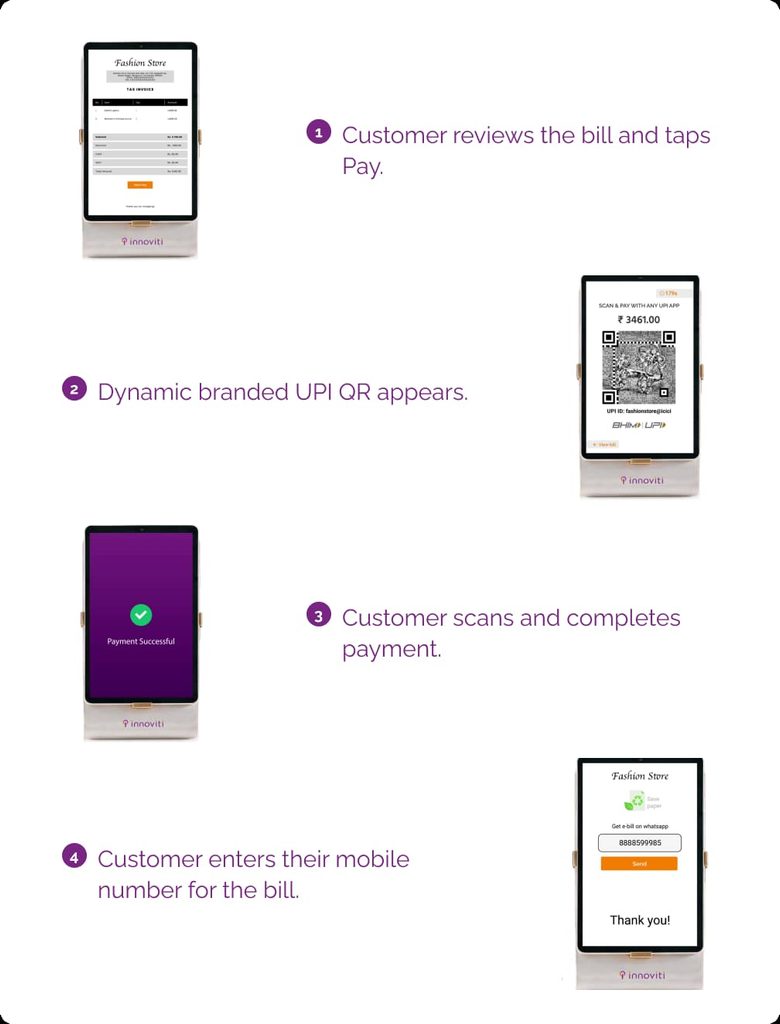
What the integration manages
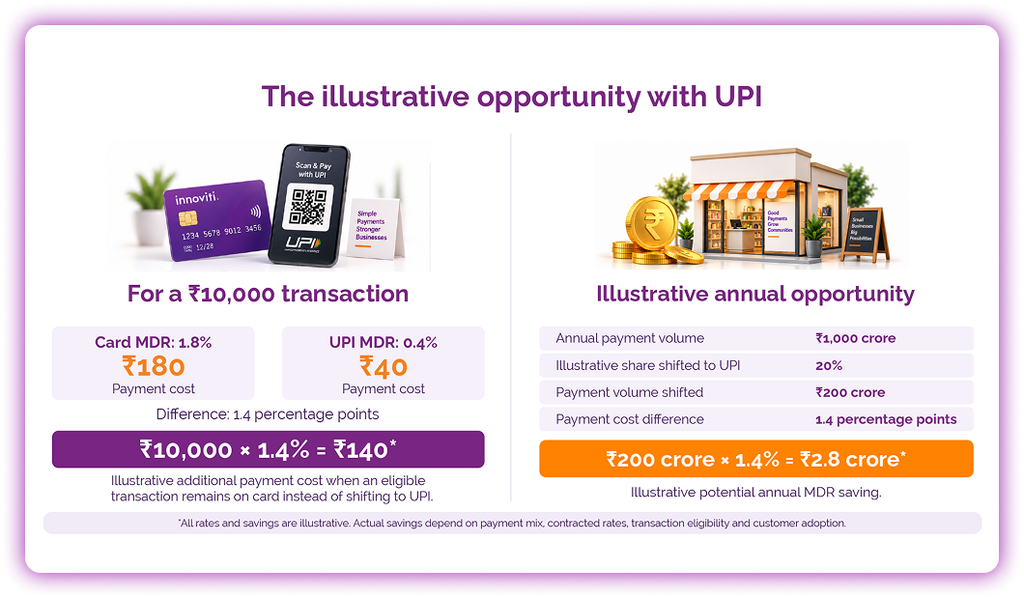
Turn UPI Adoption Into Payment Cost Savings.
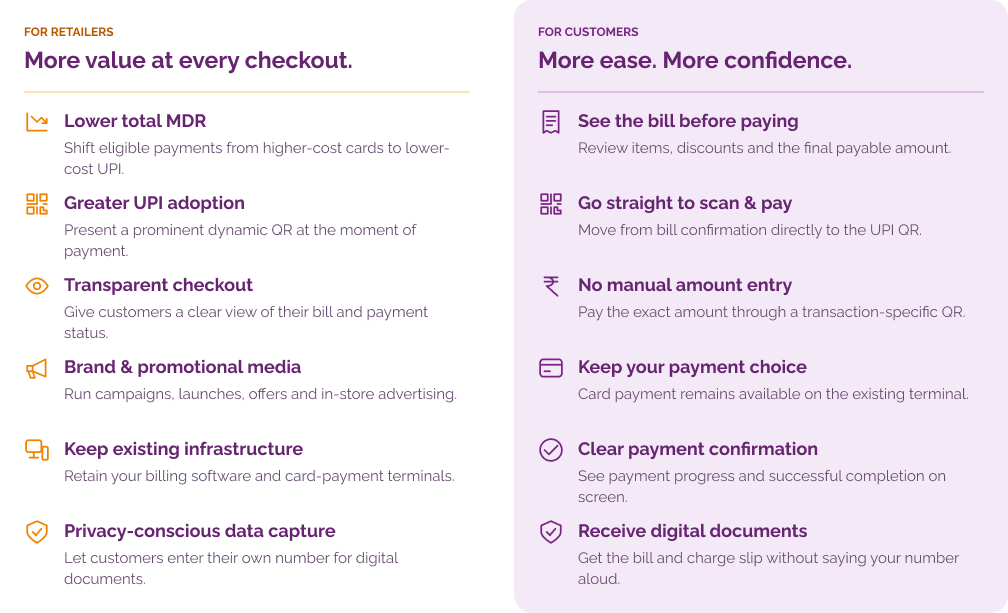
Business value for retailers. A better experience for customers.
Enterprise payment innovation built for scale
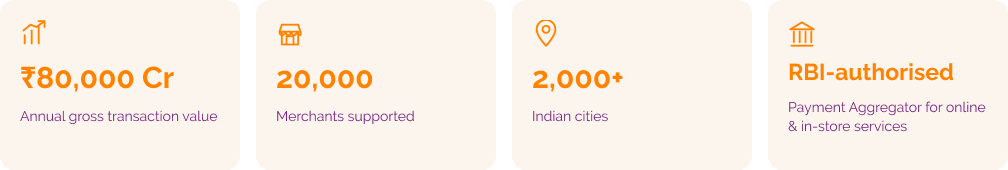
More than two decades of retail payment automation—built for enterprise retailers, multiple stores and connected customer journeys.
Every eligible transaction is an opportunity
Bring UPI-First Checkout to your stores
Give UPI the first opportunity at checkout. Speak with Innoviti to integrate with your billing environment and scale across your retail network.
Frequently Asked Questions
Could MDR increase if a customer uses a RuPay credit card through UPI?
RuPay credit cards represent approximately 20% of credit cards. Visa and Mastercard credit cards are not supported on UPI applications, so retailers can still benefit when eligible Visa and Mastercard transactions shift to bank-account-based UPI. Innoviti has also observed a 3X higher scan rate for photo-realistic QRs compared with regular QRs.
Is card payment always available?
Yes. The UPI-First Checkout display and card terminal are activated together. The customer can pay by card at any time, without the cashier cancelling or restarting the transaction. The system detects the payment method and closes the bill automatically.
How will reconciliation work with a single digital tender mode?
The payment response identifies whether the transaction was completed through card or UPI, along with the relevant bank information. Card options such as EMI and DCC remain on the terminal, allowing new payment options to be added without changing the billing integration.
What assurance is there that card transactions will shift to UPI?
Innoviti’s commercial model is linked to results. There is no additional charge for up to a 10% improvement over the retailer’s existing UPI-to-card ratio. Charges apply only when the shift exceeds that threshold.
Disclaimer
All MDR and savings calculations are illustrative. The ₹2.8 crore annual saving assumes ₹1,000 crore in annual payment volume, a 20% shift from cards to eligible UPI transactions and a 1.4 percentage-point difference in payment cost. Actual savings will vary based on payment mix, contracted rates, transaction eligibility, applicable regulations, taxes and other charges.
Discounts, cashback and promotional benefits remain subject to the eligibility rules, terms and fulfilment processes of the relevant UPI application, payment partner, sponsoring institution or campaign provider.
References to DPDP Act 2023 alignment relate specifically to the customer-led mobile-number capture flow. Overall compliance depends on the retailer’s complete data-collection, consent, storage, processing and governance practices.